Does Homeowner’s Insurance Cover Roof Damage? What Berlin, MD Homeowners Need to Know
After a nor’easter rolls through the Eastern Shore or a summer storm drops hail on Worcester County, most homeowners look up at the roof, then down at their insurance policy. The honest answer to “is this covered?” is: it depends. Coverage usually comes down to three things: what caused the damage, how well it is documented and how old the roof is.
Here is what homeowners in Berlin, MD should understand before they call their insurance company.
What Homeowners Insurance Typically Covers
Most standard homeowners policies cover roof damage from a sudden and accidental event. In plain language, that usually includes:
- Wind damage from storms, hurricanes and nor’easters
- Hail that cracks, dents or bruises shingles
- Falling trees or large branches
- Lightning strikes
- The weight of ice or snow causing structural damage
If one of these caused your damage, you likely have a claim. The key is showing that the damage ties to the weather event and not to years of wear.
What Insurance Does Not Cover
This is where most homeowners get surprised. Insurers commonly deny or reduce roof claims when the damage falls into one of these categories:
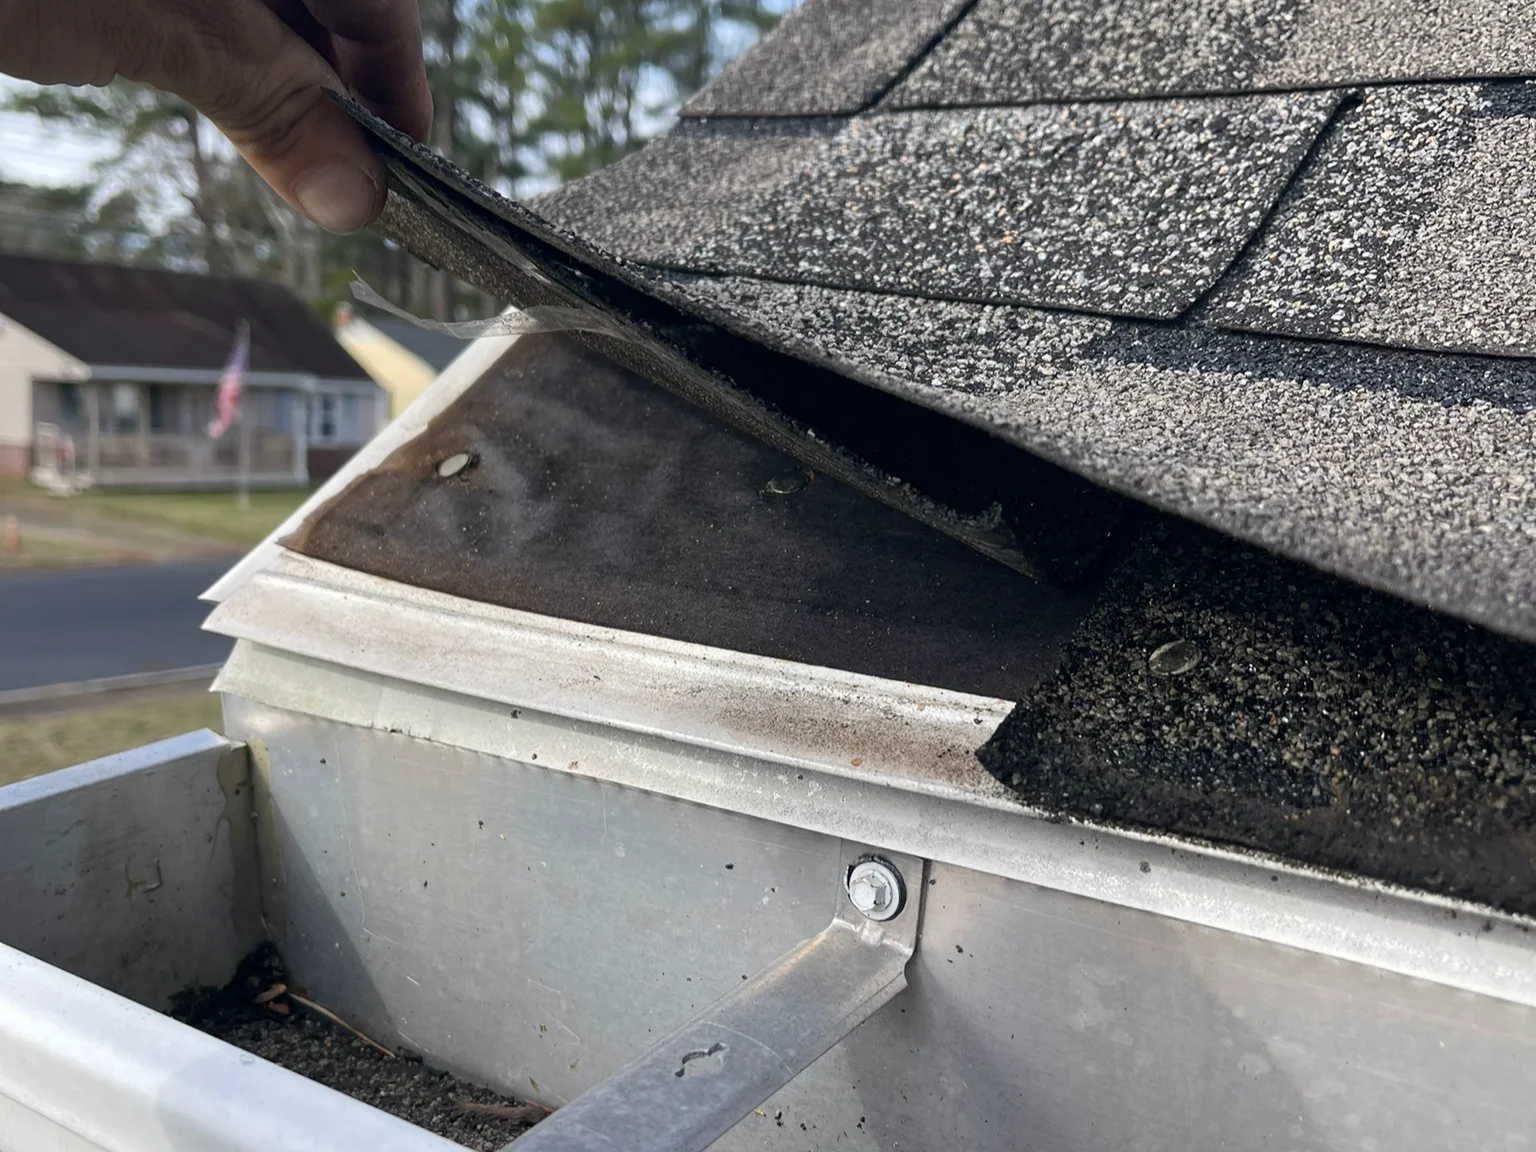
- Normal wear and tear. Granule loss, curling and fading over time are maintenance issues, not claims.
- Pre-existing damage. If the roof had problems before the storm, the insurer may argue the storm did not cause them.
- Lack of maintenance. Missing sealant around flashing, clogged gutters that led to ice dams or rotted fascia can all be used against a claim.
- Age. Many policies pay actual cash value instead of replacement cost once a roof reaches a certain age.
RCV vs. ACV: The Policy Detail That Changes Everything
Before a storm ever hits, check your policy for these two terms. The difference can be thousands of dollars.
| Replacement cost (RCV) | Actual cash value (ACV) | |
|---|---|---|
| What it pays for | A new roof at today’s prices | The depreciated value of your old roof |
| Effect of roof age | Small | Large: older roofs pay out less |
| What you pay | Your deductible | Your deductible plus the depreciation |
| Where to find it | Declarations page or roof endorsement | Declarations page or roof endorsement |
General comparison. Your policy wording controls, so ask your agent which one applies to your roof.
Many homeowners do not realize they have ACV coverage on the roof until they are holding a check that covers only part of the job. Read your policy now, while the sky is clear.
How to Protect Your Claim Before and After a Storm
Before a storm:
- Have the roof inspected every one to two years. A written report creates a baseline record of its condition.
- Keep the gutters clean and the flashing sealed. Adjusters look for deferred maintenance.
- Photograph the roof once a year. Dated photos show its condition before a storm.
After a storm:
Do a safe check from the ground. Look for missing shingles, debris and granules washing out of the downspouts.
Call a licensed roofer. A professional inspection documents the damage accurately before you file.
Avoid storm chasers. Do not let an unlicensed crew inspect or start work. Their reports often create more claim problems than they solve.
File promptly. Most policies set a deadline for reporting a loss, so check yours and do not wait.
Why Contractor Documentation Matters in a Claim
When we inspect a roof in Berlin, we document the damage in writing: photos, measurements and a written assessment of the cause. Adjusters respond to documented claims differently than to verbal ones.
G and Bros is GAF Certified Plus, family-owned since 2012, with 25+ years of Maryland roofing experience from our founder. Our reports are clear and organized so your adjuster can see exactly what we found. We document the damage; the negotiation with the insurer stays between you, your agent and, if you hire one, a public adjuster.
What to Do If Your Claim Is Denied
A denial is not always final. If your insurer denies your roof claim, you have options:
- Ask for the denial reason in writing. You are entitled to know why.
- Get a second opinion from a contractor. If the adjuster missed damage, a detailed report can support a request to reconsider.
- Contact the Maryland Insurance Administration. If you believe the claim was handled unfairly, you can file a complaint.
- Consider a public adjuster. A public adjuster works for you, usually for a percentage of the settlement.
Frequently Asked Questions
Is wind damage covered in Maryland?
On most standard homeowners policies, yes. The challenge is showing the damage came from the wind event and was not already there. A dated contractor inspection report is strong evidence.
Will filing a roof claim raise my rates?
It can. One claim over several years usually has a small effect, but several claims in a short period can lead to a rate increase or non-renewal. Ask your agent before filing for smaller damage you could pay for yourself.
My roof is 20 years old. Can I still file a claim?
Yes, but the payout may be much lower with ACV coverage, because the insurer depreciates the roof based on age. Some policies also limit coverage on older roofs, so check yours.
How long does a roof insurance claim take in Maryland?
It varies by insurer and by how complex the claim is. Having contractor documentation ready when you file helps keep things moving.
Can G and Bros help with the claims process?
We inspect the roof, document the damage in writing and can meet your adjuster on site. We do not negotiate with insurers on your behalf (that is a public adjuster’s role), but our documentation gives your claim a solid foundation.
Want a documented baseline for your roof?
G and Bros is GAF Certified Plus, family-owned since 2012, with 25+ years of Maryland roofing experience from our founder. We work in Berlin, Ocean City, Ocean Pines and across the Eastern Shore.
Get a Roof Quoteor call 410-677-4975

Recent Blog Posts