How to File a Roof Insurance Claim in Pittsville, MD: A Homeowner’s Step-by-Step Guide
After a storm rolls through Wicomico County, finding damage on your roof can feel overwhelming. Knowing what to do, and in what order, makes a real difference in how smoothly a roof insurance claim goes.
This guide walks Pittsville homeowners through the process step by step. Whether you’re dealing with wind-lifted shingles, hail damage or a leak that showed up days after the storm, the same steps apply.
Step 1: Document Everything Before You Touch Anything
The most important thing you can do right after finding roof damage is document it. Walk around the house and photograph every angle you can safely see from the ground. Don’t climb onto the roof yourself.
- Take dated photos and video of all visible damage
- Photograph the inside too: the attic, ceilings and walls where water got in
- Write down the date and time of the storm and save any weather alerts
- Keep a list of anything damaged inside the home
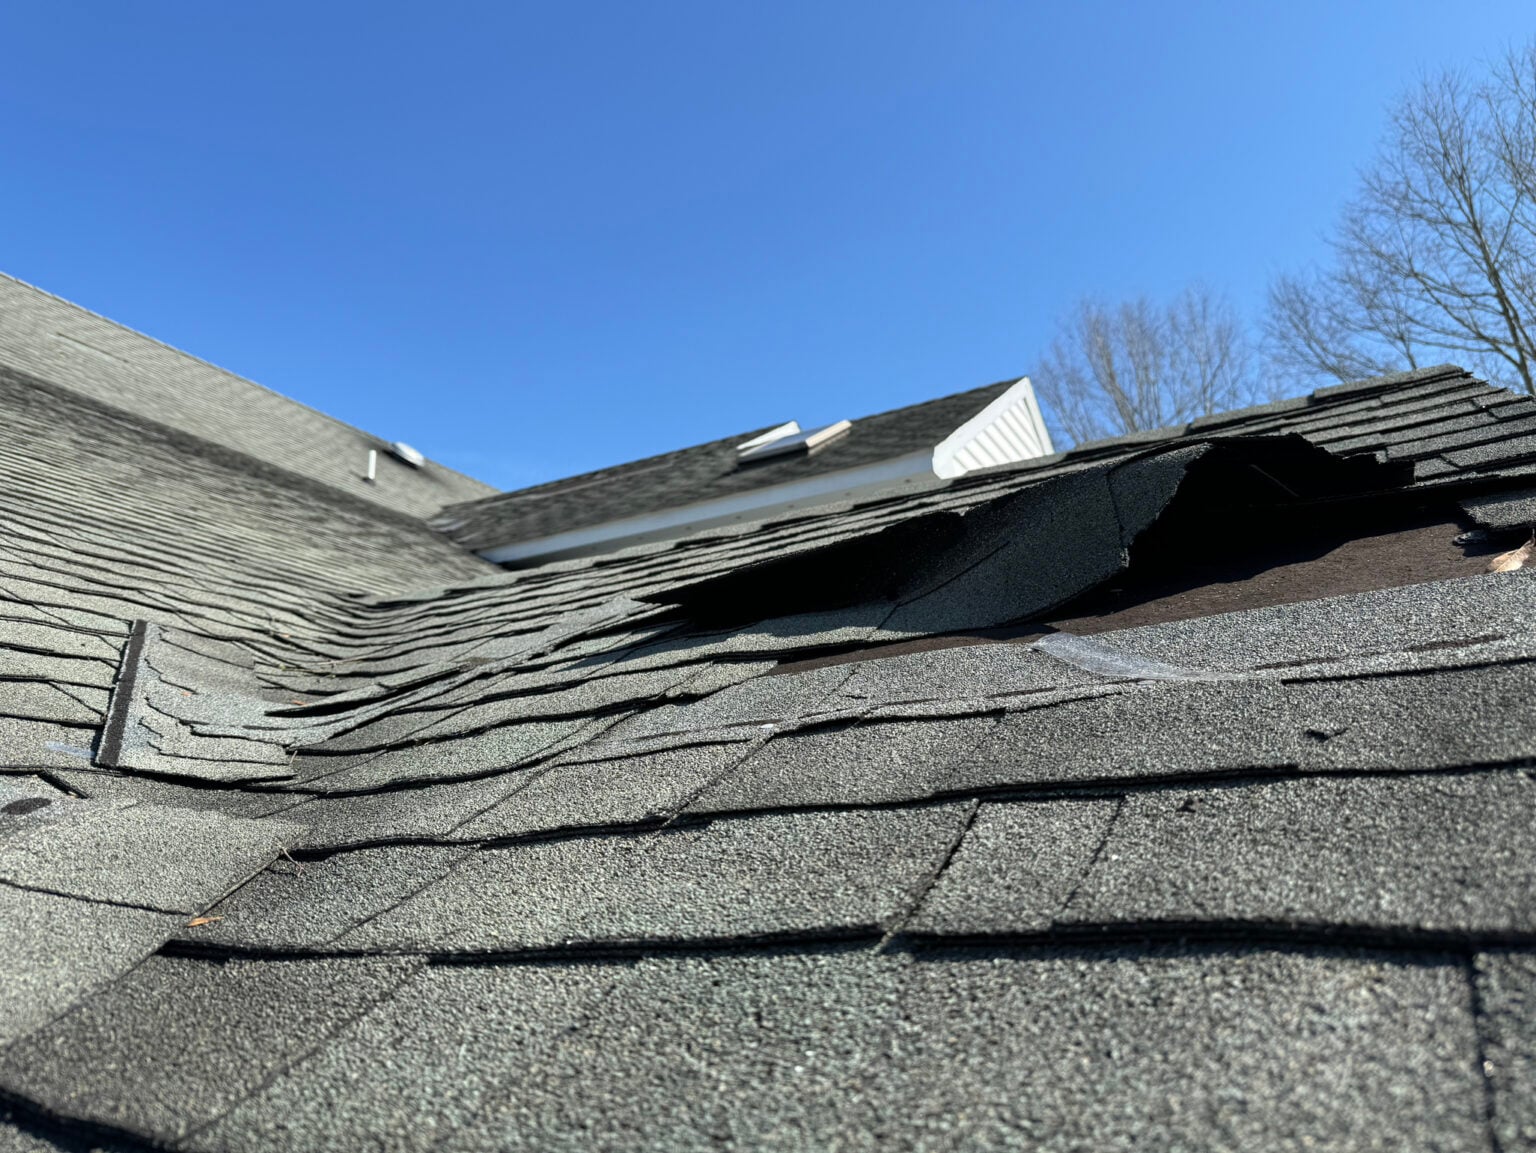
Adjusters look for documentation that ties the damage to a specific storm. The better your records, the easier your claim is to review.
Step 2: Prevent More Damage, but Hold Off on Permanent Repairs
If water is getting in, cover the damaged area with a tarp or have a roofer do it. Your policy expects you to take reasonable steps to protect the home from further damage. Save receipts for anything you spend on temporary protection.
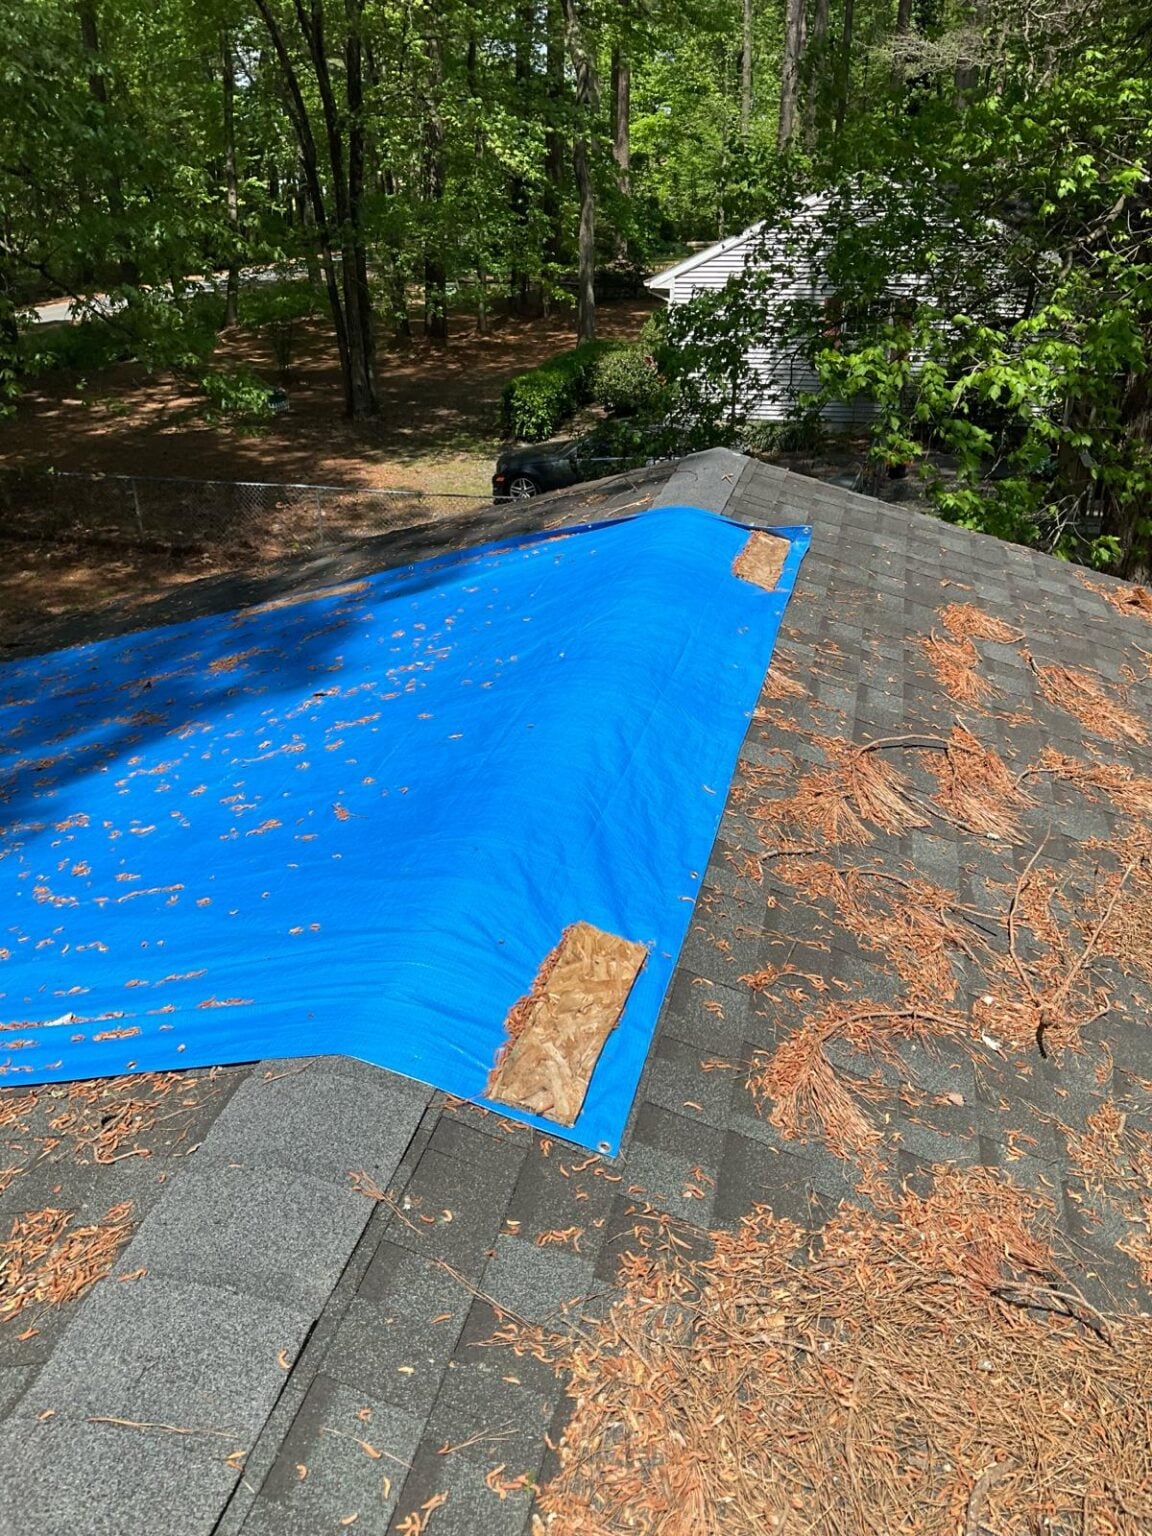
Hold off on permanent repairs until your insurer has had a chance to see the damage. Work done before the adjuster’s visit may not be reimbursed.
Step 3: Get a Professional Roof Inspection
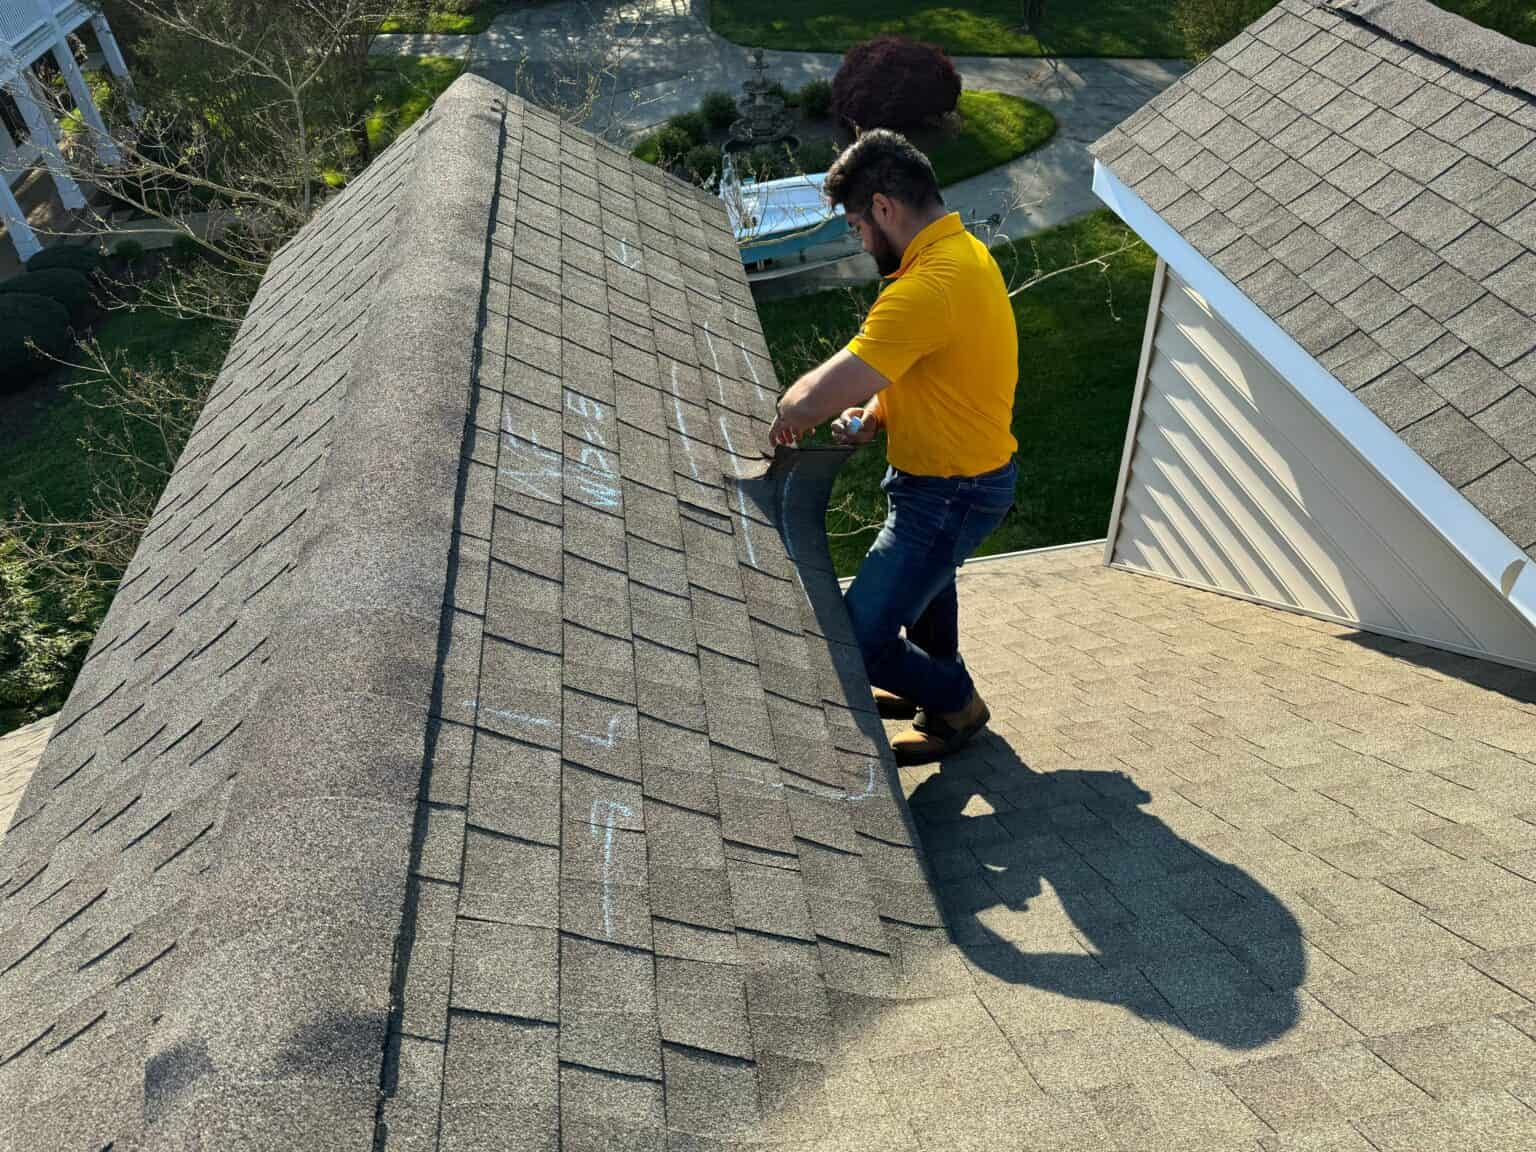
A written assessment from a licensed local roofer gives you an independent record of what’s damaged and what the repair or replacement would involve. The Maryland Insurance Administration notes that a contractor can help you see damage you might miss from the ground.
At G and Bros, we inspect the roof, photograph every affected area and give you a written repair estimate with material details. That estimate is yours to keep and share with your insurer. What we don’t do is negotiate your claim. In Maryland, only a licensed public adjuster can do that for you.
Step 4: File Your Claim Promptly
Call your insurer or agent as soon as you know there’s damage and you’ve decided to file. Most policies require prompt notice, so check yours for any deadline.
When you call:
- Have your policy number ready
- Give the date of the storm and the type of damage (wind, hail, falling limbs)
- Ask about your wind or hurricane deductible, since many policies carry a separate one for those storms
- Write down your claim number and the name of your assigned adjuster
Step 5: Understand Your Deductible and Policy Type
Eastern Shore homeowners sometimes find out too late that their wind or hurricane deductible is a percentage of the home’s insured value, not a flat dollar amount. On a home insured for $250,000 with a 2% deductible, that’s $5,000 out of pocket before coverage kicks in.
Know which kind of coverage you have:
- Replacement Cost Value (RCV): Pays what it costs to replace the roof at today’s prices.
- Actual Cash Value (ACV): Pays replacement cost minus depreciation. On an older roof, that can mean a much smaller check.
If you’re not sure which you have, ask your agent before the adjuster visits.
Step 6: Meet the Adjuster and Review the Estimate
Your insurance company will send an adjuster to look at the damage. Be there for the visit, walk them through your photos and point out any interior damage you’ve found.
When the insurer’s estimate comes in, compare it with the written estimate from your roofer. Look for:
- Missing items such as drip edge, ice and water shield or ventilation
- Material prices that look out of date
- Roof measurements that don’t match
If the numbers don’t line up, ask your insurer to explain the difference and send them your contractor’s estimate. If you want someone to argue the claim on your behalf, you can hire a licensed public adjuster.
What Insurance Typically Doesn’t Cover
Policies vary, but most homeowners policies don’t cover:
- Normal wear and tear, or shingles past their useful life
- Damage caused by lack of maintenance, like clogged gutters backing water up
- Damage that was already there before the storm
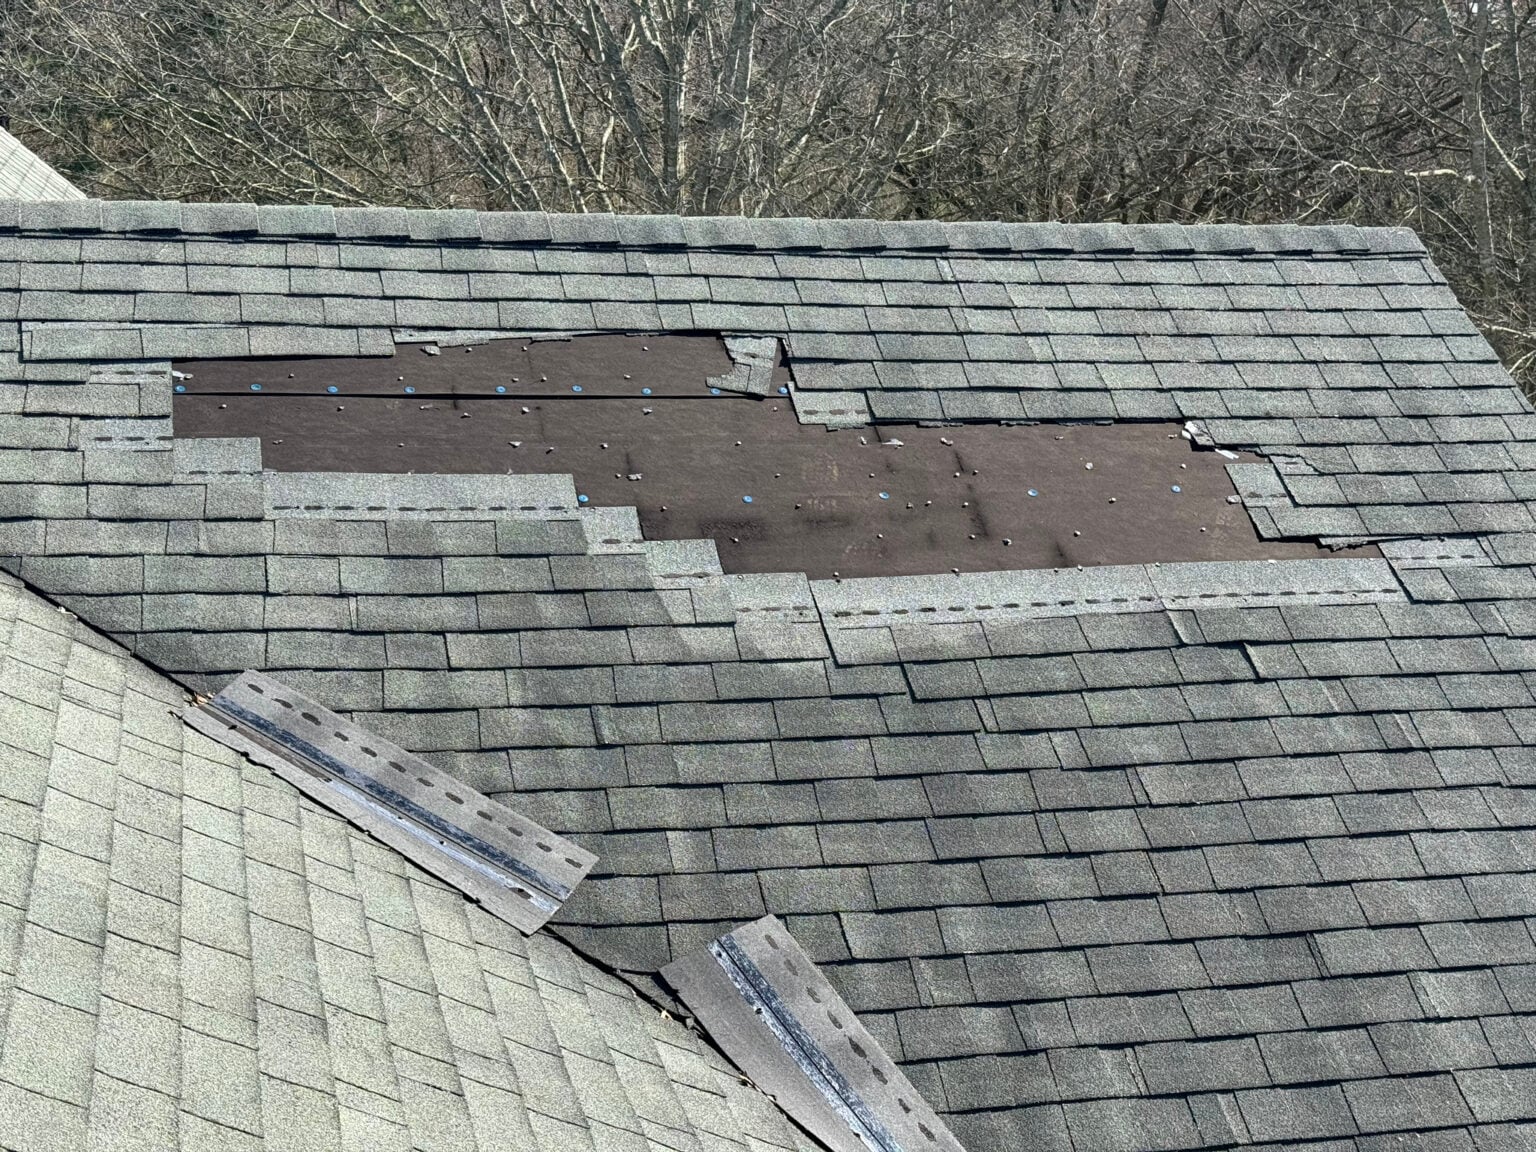
A roof repair visit or inspection before storm season gives you a dated record of your roof’s condition. That record can help if anyone later questions whether damage was already there.
A Note on Storm Chasers
After a big storm, out-of-town contractors often go door to door offering to “handle” your claim. Be careful. Under Maryland Insurance Article §27-407.2, it’s a fraudulent insurance act for a contractor to pay or promise to pay your deductible on weather-damage work that insurance pays for. The Maryland Insurance Administration also warns homeowners not to sign anything that assigns their claim to a contractor. Read their consumer advisory on free roof offers before you sign anything.
Check any contractor’s license on the Maryland Home Improvement Commission’s online database, and look for a local address and a track record. G and Bros is based at 109 Clark Street in Salisbury and serves homeowners across Wicomico County, including Pittsville, Fruitland and Eden.
Frequently Asked Questions
How long does a roof insurance claim take in Maryland?
It depends on the insurer, the damage and how busy adjusters are after a storm. Your claim stays open until the insurer has made all the payments you’re owed, and you can ask your insurer or adjuster for a status update at any time.
Will my insurance premium go up if I file a claim?
It can. How a claim affects your rate depends on your insurer and your claim history. Ask your agent before deciding whether to file for minor damage.
Can I choose my own roofing contractor for an insurance repair?
The hiring decision is yours. You can get an estimate from your own contractor and share it with your insurer. Check your policy and ask your adjuster if anything in it affects how repairs are handled.
Can a roofer handle my insurance claim for me?
No. In Maryland, only a licensed public adjuster can negotiate a claim on your behalf. A roofer can inspect the damage, document it with photos and give you a written repair estimate to share with your insurer.
What if my insurance claim is denied?
Ask your insurer for a written explanation of the denial. You can send additional documentation, such as a contractor’s inspection report, and ask for the claim to be reviewed again. You can also hire a licensed public adjuster or contact the Maryland Insurance Administration if you think the claim was handled unfairly.
Need a Roof Inspection After a Storm?
G and Bros has been family-owned since 2012, with 25+ years of Maryland roofing experience from our founder. We’re MHIC licensed and a GAF Certified Plus contractor. If your home in Pittsville or anywhere in Wicomico County took storm damage, we’ll inspect it, document what we find and give you a written estimate for storm restoration work.
Call 410-677-4975, email office@gandbros.com or contact us online to schedule an inspection.

Recent Blog Posts